Growth in a Year of Regulatory Change: What We Heard at MAACS 2026
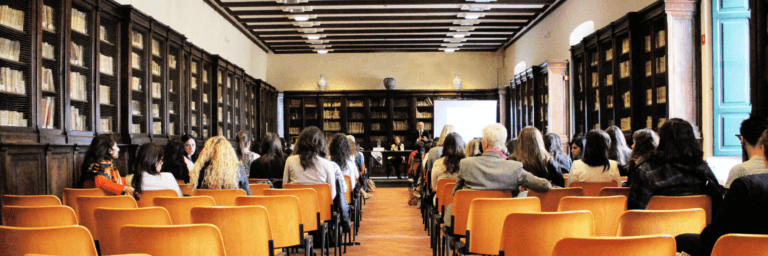
The Mid-Atlantic Association of Career Schools held its 2026 Annual Conference in Lancaster, Pennsylvania, and the highlight, for me, had nothing to do with regulation. It was watching Debbie Dunn of the Lancaster School of Cosmetology receive a lifetime achievement award and seeing the other community and education honorees recognized alongside her.
That is the part of this sector people outside it rarely see: schools built and sustained over decades by people who care about the students who walk through the door.
But the working conversation in the room was about decisions. Specifically, how to keep growing a school while the rules underneath the entire sector are being rewritten. McClintock & Associates presented twice: a session on strategic growth and complex transactions, and a session on earnings accountability — and the two sessions kept pointing at the same conclusion. Growth strategy and compliance strategy have stopped being separate conversations.
Two sessions, one throughline
Our Managing Director Dave McClintock, CPA, presented the strategic growth session with Jonathan Tarnow, Esq., of Faegre Drinker Biddle & Reath. They laid out six mission-aligned pathways for institutional growth: affiliation agreements, shared services agreements, third-party program management, organic program development, customized employer programs, and mergers and acquisitions.
The discipline that ran through all six was the same. Growth should advance the institution’s core mission, financial modeling should be honest and multi-year, and regulatory engagement should start early rather than at closing.
The earnings accountability session, which I presented, drew the most debate of the conference and covered the regulatory change that bears most directly on program-level growth decisions.
Put the two together and the throughline is hard to miss: in 2026, program-level growth or survival decisions increasingly carry a compliance dimension, and earnings accountability is a big part of why.
The growth decisions schools are weighing
This is the shift we are seeing between engagements. The earnings test is no longer arriving as an isolated compliance question. It is arriving inside growth conversations, and institutions that once treated the audit as a year-end event are bringing us in at the strategy stage — before they add a program, accelerate an online launch, open a campus, or entertain an acquisition.
The reason is that each of those moves now carries an operational and compliance consequence. Online expansion reshapes audit complexity and state-authorization requirements. A 90/10 recalculation changes the denominator math. Composite-score volatility can surprise a leadership team mid-cycle. And in any transaction, diligence now turns on composite-score defensibility and Title IV liability. Proprietary institutions have driven 53% of higher-education M&A activity since 2000 (SHEEO, 2025), and the audit chair increasingly sits at the center of those valuation conversations.
We are sitting down with executive teams more frequently to map exactly this. In one recent example, we prepared an executive discussion for the leadership team of a multi-campus allied health institution weighing its next chapter — new campuses, online program acceleration, and long-standing partnerships up for review. Rather than lead with audit scope, we framed three converging currents — the OB3 regulatory reset, capital movement across the sector, and the program-specific earnings and loan-cap exposure — as a single five-year planning window. Growth strategy and compliance strategy were not two agendas. They were one.
The regulatory change driving those decisions: earnings accountability
Earnings accountability is one of the regulatory changes reshaping program-level decisions most directly — which programs you add, grow, retire, or acquire. It is a federal framework that measures whether a program’s graduates out-earn a benchmark of working adults with less education, and ties program eligibility to that result. It comes out of the One Big Beautiful Bill Act (P.L. 119-21) and the Department of Education’s subsequent rulemaking. The Department published the final rule — “Accountability in Higher Education and Access Through Demand-Driven Workforce Pell: Student Tuition and Transparency System (STATS) and Earnings Accountability” — on July 1, 2026, closely tracking the consensus language from the AHEAD negotiated rulemaking. The first official metrics are scheduled to be released in 2027.
The framework replaces the older Financial Value Transparency and Gainful Employment (FVT/GE) approach, which used both a debt-to-earnings test and an earnings premium. Now, debt-to-earnings is removed and a single earnings premium test remains with fewer NSDLS reporting elements.
The most useful thing schools can do right now is stop guessing and look at the data. During the negotiated rulemaking, the Department released the 2026 Program Performance Data (PPD:2026). It is not the official eligibility metric, but it may be the best early-warning tool available — it lets you see roughly how your programs’ graduates are earning and which programs sit closest to the threshold, before the official numbers arrive. (For how the file is built and how the first official cohorts will be calculated, see the FAQ below.)
The near-term decision: early implementation before October 1
Here is the decision on the table right now. There is one final FVT/GE reporting cycle due October 1, 2026. Early implementation means choosing to report under the reduced STATS requirements for that October cycle instead of the legacy FVT/GE framework. Early implementation is primarily a reporting decision — the new earnings test is coming in 2027 either way.
At the time of the conference, MAACS leadership advised against early implementation. In later meetings and discussions, however, that position evolved, and early implementation came to be viewed as the safer course.
There is also relief in the new rule: a limited enforcement delay for programs preparing students for tipped-income occupations. The Department built the list — Table 5.22 — from Treasury/IRS tip data using a CIP-to-SOC crosswalk, and it captures the full cosmetology category, massage therapy programs, and select bartending and casino-operations programs. The logic is the “No Tax on Tips” provision, which takes effect for the 2026 tax year. During the delay, affected programs are neither passed nor failed — but the Department still calculates and publishes the underlying earnings data, so a “low earnings” flag could still appear on the College Scorecard and surface on the FAFSA.
What’s still contested
The room raised objections that have not been resolved, and I share them. The test compares recent completers, many in their early twenties, against working adults aged 25 to 34 who have had more time in the labor market. It measures earnings against a state-level benchmark that ignores regional cost-of-living and rural labor markets. Some individuals who completed a vocational program appear to be counted in the ACS comparison group as people who never attended college. And the appeals process is extremely limited.
The litigation front is also still live. The American Association of Career Schools (AACS) – formerly the American Association of Cosmetology Schools – challenged the Department’s 2023 gainful employment rule; the district court upheld the rule, and the case is expected to continue on appeal. If AACS ultimately prevails, it would meaningfully strengthen the argument that undergraduate certificate programs should be excluded from the new earnings accountability framework — sometimes called “Do No Harm” — which is one of the genuinely open questions about how far this framework can statutorily reach.
There is a broader point worth carrying home, too. This is the first cycle in which earnings accountability applies across every sector of higher education — public and non-profit institutions that have never faced a program-eligibility test are now navigating one alongside career schools. For years this sector argued “treat us the same.” This is, in a rough and painful way, that argument coming true, with career schools absorbing a disproportionate share of the early impact while the traditional sector catches up.
McClintock’s Perspective — and what to do now
The institutions navigating this well share one habit: they treat program-mix and growth decisions as compliance decisions, and they pull their advisors in early rather than at close. Program eligibility is no longer a compliance-office topic — it is a board- and ownership-level issue, because a program can now lose eligibility, and that belongs in front of the people who set enrollment strategy and approve new programs.
Three things to do now:
- Model your exposure before you decide anything. Pull PPD:2026, identify which programs sit near the earnings threshold and which lack the completers for a calculated result. This is your risk map.
- Make the October 1 call deliberately. Decide whether staying on FVT/GE for one final cycle or moving to STATS better protects you. If you stay on FVT/GE, complete every element.
- Put growth and compliance in the same room. Before you add a program, launch online, open a campus, or explore a transaction, model the earnings, 90/10, and composite-score implications alongside the strategy.
Earnings accountability is painful, but it does not have to be mysterious — and the growth decisions it touches do not have to be made blind. Legal challenges could still affect the timing, but the framework now explicitly rests in statute, which gives it staying power, and the schools that will navigate it best are treating the next several months as a modeling and decision problem with real data in front of them.
McClintock & Associates works with postsecondary institutions to model earnings exposure using the PPD:2026 file, evaluate the October 1 reporting decision, and build growth and compliance strategy as a single plan. If you want a focused, time-boxed OB3 consulting engagement to pressure-test where your programs stand and what your next growth move means, we can help you run it.
Frequently Asked Questions
Earnings accountability is a federal framework, finalized by the Department of Education on July 1, 2026, that measures whether a program’s graduates out-earn a benchmark of working adults with less education. It replaces the debt-to-earnings component of Gainful Employment with a single earnings premium test and ties Direct Loan program eligibility to the result. It stems from the One Big Beautiful Bill Act (P.L. 119-21). The first official metrics are scheduled for release in 2027.
Every growth choice now carries a compliance dimension: online expansion reshapes audit complexity and state-authorization requirements; a 90/10 recalculation changes the denominator math; and acquisition diligence turns on composite-score defensibility and Title IV liability. Institutions increasingly bring McClintock into these decisions at the strategy stage, not just at audit time.
It is a reporting decision. There is one final FVT/GE reporting cycle, due October 1, 2026. Early implementation means reporting under the reduced STATS requirements for that cycle instead of the legacy FVT/GE framework. If you stay on FVT/GE, complete every data element — an incomplete submission can be treated as a choice to move to STATS.
In the public PPD:2026 preview, results are reported at the 4-digit CIP level (grouping related programs such as cosmetology and esthetics). The cohort is completers from the 2017-18 and 2018-19 award years, earnings are from tax year 2023 adjusted to 2024 dollars, the benchmark draws on ACS earnings thresholds, and small cohorts are suppressed. The first official calculation will use earnings year 2025 and an initial completer cohort from the 2020-21 award year; if a program has fewer than 30 completers, the Department works backward across four award years, then aggregates within the same 4-digit CIP, and if the cohort is still too small, does not calculate a metric.
Programs preparing students for tipped-income occupations, identified in Table 5.22 of the final rule — nearly all cosmetology programs (CIP 12.04), plus barbering, certain massage therapy programs, and select bartending and casino-operations programs. During the delay these programs are neither passed nor failed, but the Department still calculates and publishes their earnings data, so a low-earnings flag can still appear on the College Scorecard and FAFSA. You may also have a multi-year delay if the cohort expansion is needed for next year’s earnings test.
The American Association of Cosmetology Schools challenged the Department of Education’s 2023 gainful employment rule. The district court upheld the rule, and the case is expected to continue on appeal. If AACS ultimately prevails, it would strengthen the argument that undergraduate certificate programs should be excluded from the new earnings accountability framework. As of publication, the litigation is unresolved and the rule remains in effect.
Sign up for our newsletter to stay up to date or schedule a consultation with our experts to model your impacts, develop strategies, and implement solutions.
Luke Hoey is a member of the Title IV compliance team at McClintock & Associates, P.C.